Papers & projects

Research.

Macroeconomics, monetary policy, housing, and the labour market.

Published papers

Assessing Australian Monetary Policy in the Twenty-First Century

2022 · Economic Record, 98(322), 271–295 · with Andrew Leigh

Read abstract

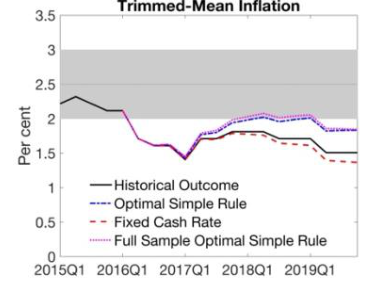
Using the Reserve Bank of Australia’s MARTIN model we compare actual monetary policy decisions to a counterfactual in which the cash rate is set according to an optimal simple rule. We find that monetary policy played a crucial role in avoiding a potential recession in 2001 and mitigating the downturn in 2008-2009. By contrast we find that the cash rate was too high during 2016-2019, keeping inflation below the Reserve Bank’s target band. Optimal monetary policy in 2016-2019 would have involved a substantially lower cash rate and would have produced significantly better employment outcomes.
Read paper (PDF)
Figure 5, inflation panel: actual and counterfactual inflation, 2016–2019View figure in paper

Optimal policy design in nonlinear DSGE models: An n-order accurate approximation

2021 European Economic Review, with Hansen J.

Read abstract

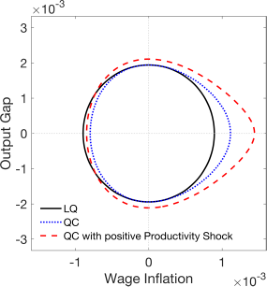
We derive an n-order accurate approximation of optimal policy for a wide class of nonlinear DSGE models analytically. Using Taylor polynomials to approximate welfare and the equilibrium, the (n; n + 1) approximation relaxes symmetry in the objective and certainty equivalence in the solution, as implied by a Linear-Quadratic (LQ) approximation with n = 1. When n > 1, we illustrate how curvature in preferences and the constraints can affect optimal policy, deriving a solution that is n-order accurate as opposed to first-order accurate only. Comparing solutions when n = 2 (a Quadratic- Cubic approximation) and n = 1 (LQ), in a New Keynesian economy with nominal frictions, we find significant differences in the optimal response to shocks; the joint distributions of wage inflation, the output gap and nominal interest rates; welfare and accuracy.

Read paper (PDF)
Figure 1, wage-inflation panel: policy preferences after a productivity shockView figure in paper

Commodity Price Volatility with Endogenous Natural Resources

2018 European Economic Review, with Hansen, J.

Read abstract

Natural resource reserves are exogenous in models of small commodity exporters. We consider richer supply dynamics and model exploration and depletion. These are important for capturing the effects of commodity price shocks including a commodity currency and crowding-out of non-commodity activity. We also consider how welfare and the ranking of optimal monetary and taxation policies change. Without exploration or depletion, optimal monetary and taxation policies can efficiently stabilise the economy in response to commodity price shocks. However, when exploration and depletion are accounted for, changing interest rates to offset price shocks becomes inefficient. Using taxation policy, specifically an ad valorem royalty, remains efficient.

Read paper

Working papers

Housing and household behaviour

The Presale Price Premium Puzzle

Revise and resubmit, AEJ: Macroeconomics · with Miroslav Gabrovski

Read abstract

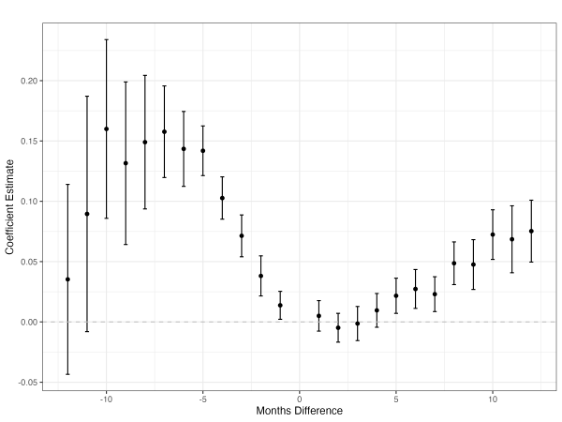
Using two and a half decades of microdata from the Survey of Construction, we document a robust presale price premium: houses sold before construction commences sell at an average of 2.8% more, with premiums reaching 15% for homes sold five or more months before construction starts. Houses sold post completion of construction also carry a modest 1.4% premium, creating a distinctive U-shaped pricing pattern. To explain this pricing pattern, we develop a search-theoretic model of the housing market in which developers face credit market frictions. We show that these credit frictions give rise to a novel channel that can rationalize the existence of both the presale and post completion premia. A calibration of our economy to the US housing market implies the credit frictions channel can explain about a third of the presale premium.

Read paper (PDF)
Figure 2(a): the U-shaped presale price premiumView figure in paper

NIMBYism and Housing Supply

with David Chivers

Read abstract

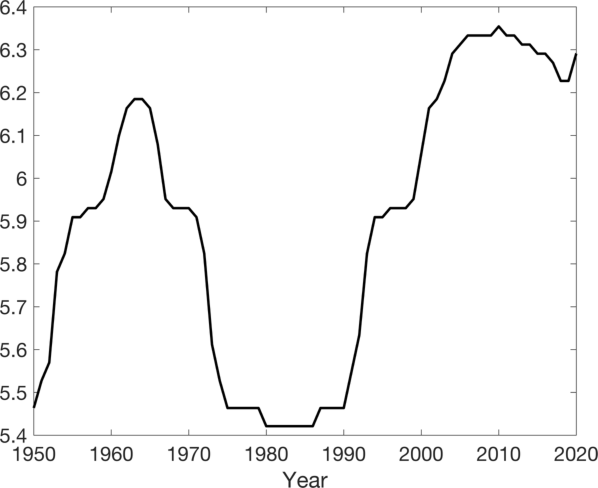
We develop a political economy model of the housing market where new housing supply is determined by a democratic vote. Support for additional supply depends on its impact on households’ utility via house prices and is strongest among younger, low-income, or renting households. Simulations show that a temporary baby boom raises homeownership and wealth for the boom generation but leads to higher house prices, lower homeownership, and reduced wealth for subsequent generations. Demographic changes and this political economy mechanism account for a 15% increase in house prices since 1950.

Read paper (PDF)
Figure 5: demographic effects on equilibrium house pricesView figure in paper

Anticipated House Purchases and Household Consumption

Read abstract

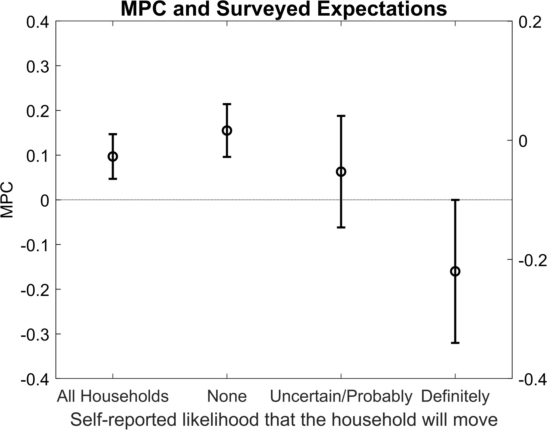
This paper evaluates how anticipated purchases of housing affect households’ consumption of non-durable goods. I build a non-linear, heterogeneous agent model in which households save in liquid assets and illiquid housing, where the latter can be used as collateral for borrowing. I show that it is able to replicate the empirical distributions of income and wealth within the US economy. In the model there is substantial heterogeneity in households’ marginal propensities to consume. Households with a high probability of buying housing stock lower their consumption of non-durable goods in anticipation of being credit constrained after their purchase. This results in households with low, even negative, marginal propensities to consume. I verify the model’s predictions using micro-data from the PSID to show that (i) consumption falls in anticipation of, and after, changes in the stock of housing and (ii) households who are planning on purchasing housing have negative marginal propensities to consume. Finally, I use this model to examine the general equilibrium effects of tax credits for first home buyers and show that they lead to decreases in aggregate consumption.

Read paper (PDF)
Figure 5, survey panel: consumption responses by expected likelihood of movingView figure in paper

Monetary policy

Buy Low, Sell High: The Case for Equity QE

Read abstract

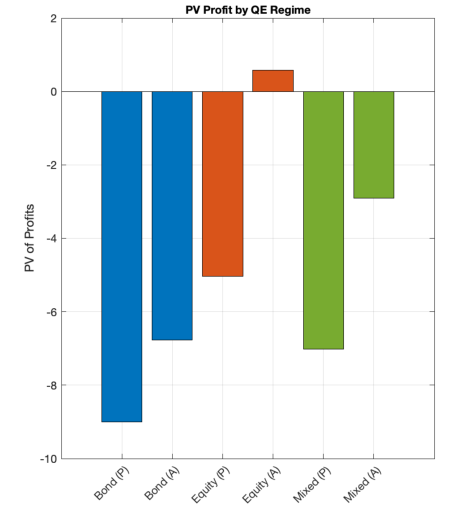
Does the composition of central bank asset purchases affect profitability and welfare? We study this question in a New Keynesian model with two household types, Gertler-Karadi financial intermediaries with asset-specific divertability, long-term government bonds, equities, and an explicit central bank balance sheet with profit accounting. For demand and monetary policy shocks that drive the economy to the zero lower bound, equity-based quantitative easing generates substantially smaller losses than bond-based QE—and near-zero losses under active unwinding. The mechanism is an asset-price asymmetry: bond prices are elevated at the ZLB (the central bank buys high), while equity prices are depressed (it buys low). Welfare effects are small but systematically favor equity QE for restricted households via the fiscal channel. Our results provide a structural explanation for the divergent portfolio outcomes of the Bank of Japan’s equity purchases versus Western central banks’ bond-heavy programs.

Read paper (PDF)
Figure 5, present-value panel: central bank profits across QE strategiesView figure in paper

AI and the labour market

Kookaburras in the Coal Mine? Measuring AI Disruption with Administrative Data

Read abstract

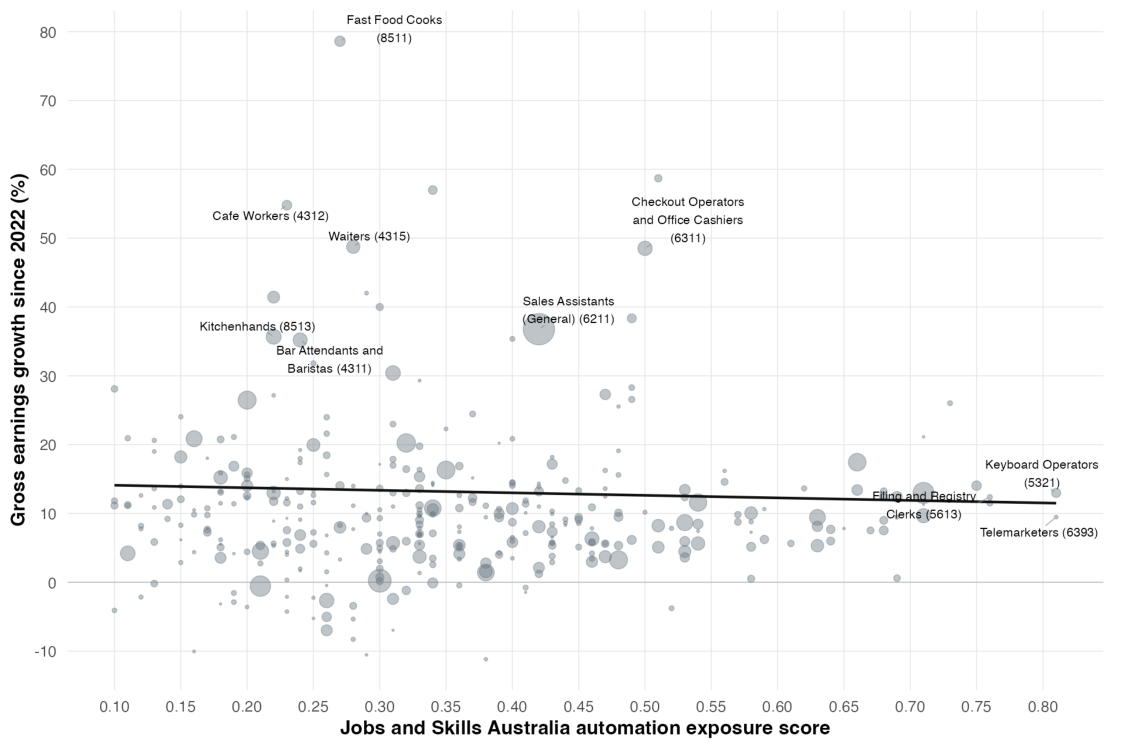
There is little evidence of artificial intelligence (AI) related job displacement as of October 2025 according to administrative data. I use Single Touch Payroll data, which tracks all Australian payroll data in close to real time, linked with both Census and firm tax data to compare post-2022 earnings and hiring across occupations with different exposure to being replaced by AI. Aggregate gross earnings has risen strongly since 2022, and there is at most a mild negative correlation between gross earnings growth and AI exposure at the occupation level, with little evidence of a stronger pattern by age. Attributing the full correlation between exposure and earnings growth to AI implies an annualised gross earnings growth reduction of 0.03 percentage points, i.e. about 0.03%. There is some evidence of labour-market displacement for workers employed at firms with a pre-LLM investment in AI. Overall, I show that high-frequency administrative data cannot find any major labour-market effects from the spread of AI.

Read paper
Figure 3(a): AI exposure and gross earnings growth across occupationsView figure in paper

Research in progress

Double Down: How Downwardly Rigid Wages Affects the Economy at the Zero Lower Bound

Read abstract

We build a non-linear New Keynesian model to investigate the interaction between two asymmetric rigidities: the lower bound on nominal interest rates and the inability for nominal wages to decrease. We show that downwardly rigid wages can either amplify or mitigate the welfare loss caused by the zero lower bound depending on the weight the central bank places on stabilisation inflation over the output gap. Finally, we show that the optimal rate of inflation is increased by the presence of both nominal frictions, when modelled either separately or in tandem, and is 2.5 per cent in the baseline calibration.

Tariff Uncertainty and Optimal Policy